Read the Policy Before the Reef: A U.S. Diver's Guide to Insurance Fine Print
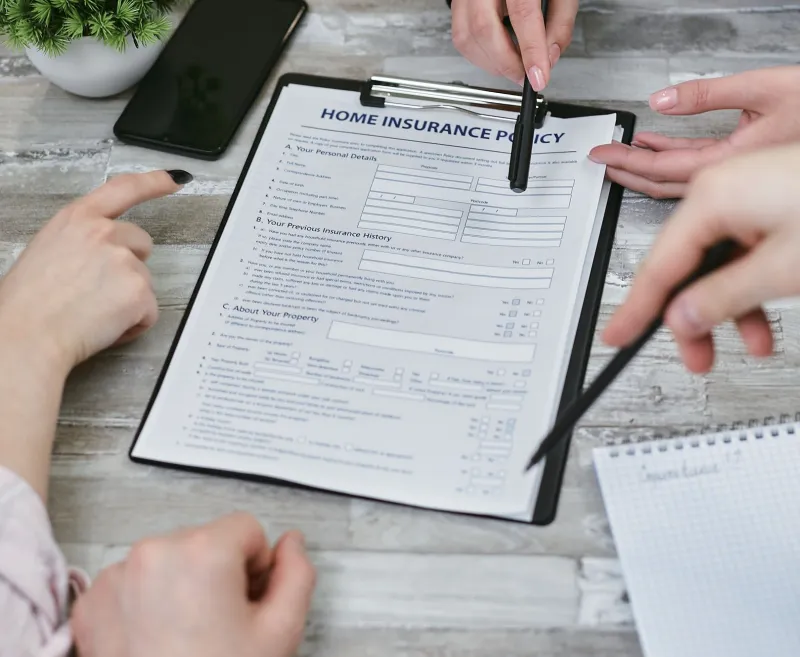
Nobody books a dive trip because they are excited about the insurance policy. But ten minutes with the fine print now can save you a season of fighting a claim later. The trick is knowing what you are actually buying.
Travel Insurance Is Not Dive Insurance
A general travel policy may cover trip cancellation, lost bags, and a sprained ankle on the beach. It may also exclude scuba diving entirely, or cover it only under limited conditions. That is the first gap to check. Look for the words scuba diving in the coverage section, not just in the activity list of a brochure.
Dive-specific coverage usually focuses on two things: treatment for dive-related injuries and emergency evacuation from remote water. General travel medical coverage may help with the first and fall short on the second. If you are heading to a liveaboard, a remote island, or a stretch of coast where the nearest chamber is a boat ride and a flight away, evacuation is the line item that matters.
Depth Limits Are Not Decoration
Many policies set a maximum depth for recreational diving. Common limits include 100 feet or 130 feet, but they vary. If your dive plan includes a deeper wreck or a wall that bottoms out beyond the limit, your coverage may not follow you. Read the definition of recreational diving, too. Some policies exclude decompression diving, solo diving, overhead environments, and dives that exceed your certification level.
This is not abstract. If you are an Advanced Open Water diver booked on a deep wreck trip, confirm that the policy covers the depth you will actually dive. If you are a newer diver, confirm that your certification level matches the dive profile the operator is running. Insurers ask those questions during claims for a reason.
Certification, Solo Diving, and the Fine Print That Bites
Many policies require that you dive within your training and with a buddy. If you are certified for solo diving and plan to use it, check whether the policy recognizes that certification. If you are diving with a guide, confirm that guided diving is treated the same as buddy diving. If you are taking a course, ask whether training dives are covered.
Also look at the pre-existing condition rules. A doctor's note may not be enough if the condition was not disclosed at purchase. U.S. health insurance may cover some care at home, but it often does not follow you to a foreign hospital or a hyperbaric chamber. That is where a dive accident policy or travel medical plan earns its keep.
Evacuation Is the Expensive Word
Emergency evacuation can mean a helicopter, a chartered boat, or a medical flight. The cost can climb fast, and the definition of medically necessary evacuation varies by policy. Check whether evacuation is coordinated by the insurer, whether you need pre-approval, and whether the policy pays upfront or reimburses you later. A policy that reimburses is fine if you have the cash and the patience. A policy that coordinates is better if you are lying on a dock in a country where you do not speak the language.
Five Questions to Ask Before You Buy
- Does this policy cover scuba diving as a named activity, not just a general recreation?
- What is the maximum depth, and does it match my trip plan?
- Does it cover emergency evacuation to a hyperbaric chamber, and who arranges it?
- Are solo diving, decompression diving, and training dives included or excluded?
- What documentation will the insurer want after an incident?
Write the answers down. Save the policy on your phone and in the cloud. Keep a copy of your certification card and your dive log with your travel documents. If something goes wrong, the claims process moves faster when the paperwork is already in order.
What to Keep in Your Dry Bag
Bring your certification card, proof of insurance, emergency contacts, and a basic medical information sheet. If you are on a liveaboard, ask the operator what they require before boarding. If you are diving internationally, check whether the policy requires you to contact the insurer before treatment or within a certain number of hours after an incident.
The goal is not to obsess over worst-case scenarios. It is to make the boring decisions now so you can make good decisions underwater later. Read the policy before the reef. Your future self will thank you.